



Prepare the project documents
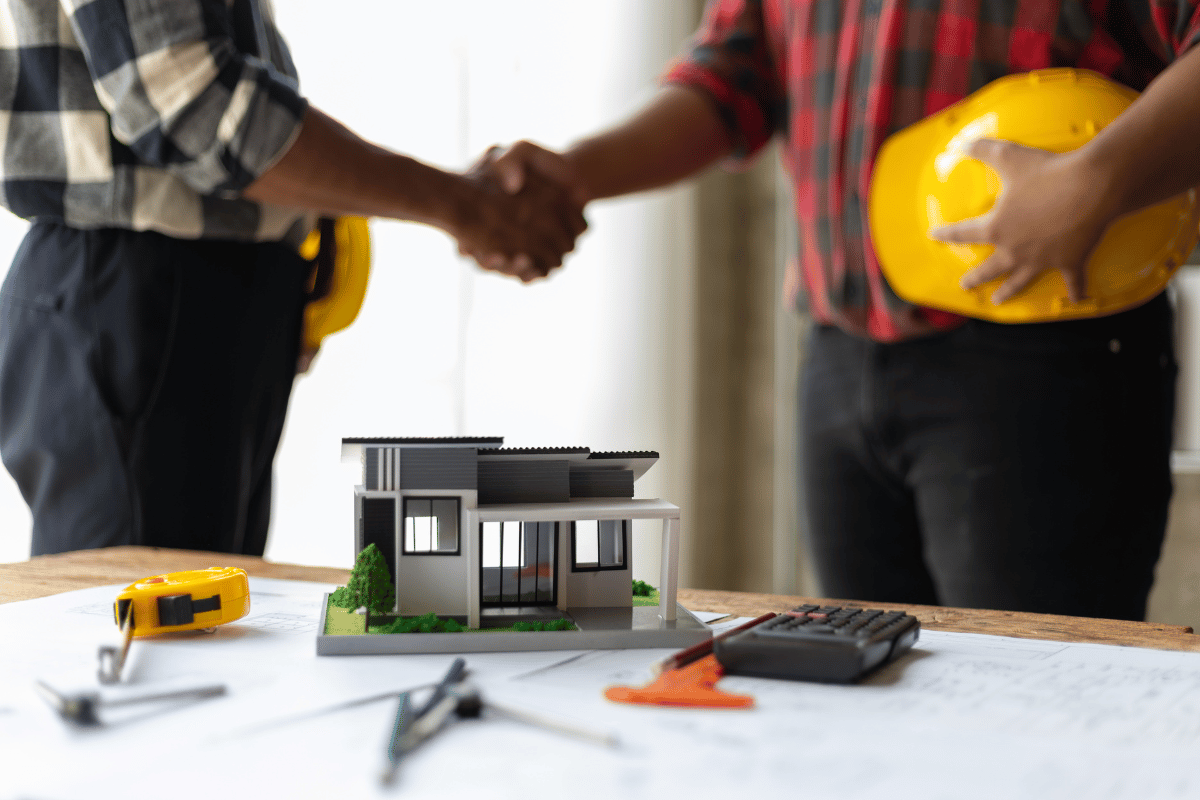
Lenders commonly require approved plans, specifications, builder details and a signed building contract before the construction facility can proceed.
CONSTRUCTION LOANS
Construction finance works differently from a standard home loan. We help you understand the lender process, project costs and progress payments before building begins.
Talk through your construction loanBEFORE THE FIRST DRAWDOWN
Construction lending depends on more than borrowing capacity. The plans, building contract, valuation, contribution and progress-payment schedule all need to work together.
Lenders commonly require approved plans, specifications, builder details and a signed building contract before the construction facility can proceed.
Funds are generally released as agreed stages are completed. Builder invoices and, in some cases, lender inspections are part of the drawdown process.
Variations, site costs, finishing work and delays can affect the final budget. A useful finance plan leaves room for costs the base contract may not cover.
FROM APPROVAL TO COMPLETION
The lender generally assesses the proposed completed property using the plans, specifications, contract and expected end value. That valuation can affect the approved loan and the contribution required.
During construction, funds are usually drawn progressively rather than released in one amount. Interest is generally charged on the amount drawn at each stage, subject to the loan terms.
At completion, the lender's final requirements are met and the facility generally moves into its ongoing home-loan repayment structure.
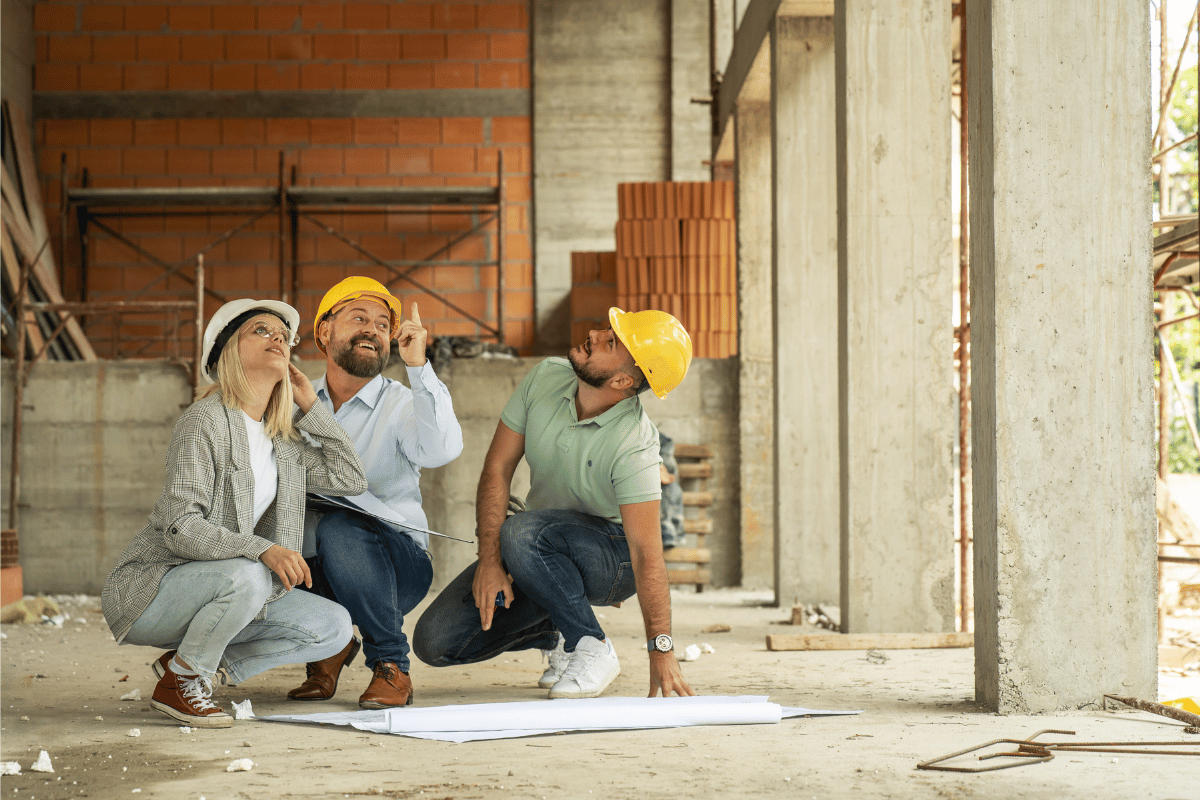
The completed-property valuation helps determine the lender's position. If it is lower than expected, additional funds or a change to the project may be required.
Acceptable builders, contract types, insurance and documentation vary by lender. Checking these requirements early can reduce avoidable delays later.
Building projects change. A sensible plan considers variations, timing changes and other costs before they become a funding problem midway through construction.
Raise Wealth Pty Ltd trading as The Digital Brokerage is a Credit Representative (553369) operating under Australian Credit Licence 389328.
FREQUENTLY ASKED
Clear answers to the questions clients often ask before applying.
Construction loan funds are generally released in stages as the build reaches agreed milestones. Builder invoices are usually required and the lender may arrange inspections before releasing funds.
Generally, interest is charged on the amount drawn rather than the full approved facility during construction. The exact repayment arrangement depends on the lender and loan terms.
Lenders commonly ask for approved plans, specifications, builder details, a signed building contract and evidence of relevant insurance or approvals.
Variations or unexpected costs may require extra funds from you and can affect the loan. It is worth allowing a buffer and understanding how the lender treats changes before construction starts.
It can be appropriate for substantial structural renovations where funds need to be released in stages. Smaller projects may suit a different finance structure, depending on the circumstances.
We can help you choose
Tell us what you’re planning. We can explain your options, compare relevant lenders and help you work out your next step.
Start with discovering your borrowing capacity by using our free calculator, then we can help you compare suitable lenders, organise the application online and manage the steps through approval and settlement.

Estimate what you may be able to borrow and talk through your income, expenses, deposit and lending goals with a mortgage broker.
We compare suitable loan options, then help you provide the information and documents needed to submit your application online.

We coordinate lender questions, requirements and key milestones, helping keep the application moving from approval through to settlement.
Loan features
Offset accounts, redraw, repayment options and rate structures can change how your loan works. Explore the key features and understand what they mean for you.
Explore all loan features →Keep savings accessible while reducing the balance used to calculate home loan interest.
Explore feature →02Understand how extra repayments can reduce interest while keeping funds available for later.
Explore feature →03Compare repayment certainty, flexibility and the trade-offs of fixing your rate.
Explore feature →04See how paying more than the minimum can reduce your loan balance and total interest.
Explore feature →05Learn how combining fixed and variable portions can balance certainty with flexibility.
Explore feature →